Kitchen and Bathroom Fitter Insurance
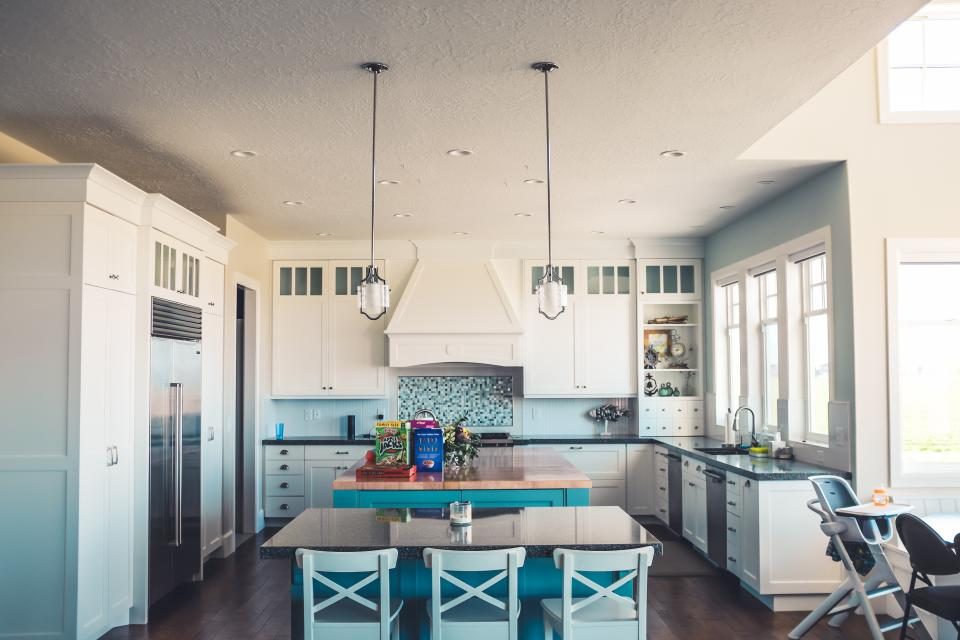
A kitchen fit is five trades in one week, in somebody's house, while they are living in it. Carpentry, plumbing, tiling, electrics and sometimes gas, and the customer holds you responsible for every part of it regardless of who actually did which bit.
The Two Claims That Dominate This Trade
Two claims dominate. Water, because both of the rooms you work in exist to move it around, and worktops, because a templated stone top is heavy, brittle, made for one kitchen and cannot be replaced this week.
The worktop one catches people out, because most fitters assume their public liability covers it and it does not.
You will see this called kitchen fitter insurance, kitchen fitters insurance, bathroom fitter insurance or bathroom fitters insurance, and plenty of people search for insurance for kitchen fitters or insurance for bathroom fitters instead. Where a firm does both it is usually written as kitchen and bathroom fitter insurance. Installers get their own spellings again, so kitchen installers insurance, bathroom installer insurance and bathroom installation insurance all land in the same place, and if you fit wardrobes and studies then bedroom fitters insurance and fitted furniture installers insurance belong here too. It is one cover with a lot of names.
What does not belong here is commercial fit out. If you are fitting out shops, offices or restaurants rather than working in people's homes, that is shopfitting, it is rated on the building around you rather than on water, and it has its own page.
How Much Is Kitchen & Bathroom Installers Insurance?
Cover for a sole trader kitchen or bathroom fitter with up to £2m of public liability starts at £86 a year. That is the entry point rather than the average: one person, liability only, with nothing for tools, employees or the job itself. Employ anyone and employers' liability becomes a legal requirement, and from there the price is driven by wageroll and by the work you take on rather than by the trade.
We are a broker, so we take it to several insurers rather than quoting one. Call 02382 000820 for a quote.
What Kitchen & Bathroom Installers Insurance Covers
Public Liability Insurance
Injury and damage to other people's property, which here means the customer's home and, in flats, the neighbour's. Limits start at £1m and step up through £2m, £5m and £10m, and working above other people is what takes a contract up it.
Employers' Liability Insurance
Legally required as soon as you become an employer, subject to limited exemptions, and included as standard. On this trade that is usually most of the people on the job.
Contract Works And Goods In Transit
The installation in progress and the goods before they go in. Units, appliances and worktops often sit in a customer's garage for days, which is neither your premises nor covered by default.
Tools & Equipment Cover
Power tools, jigs and tile cutting kit, with the usual overnight vehicle conditions.
Why Flats Change The Number
A leak in a house is a conversation with your customer. A leak in a flat is a claim from the person underneath, their insurer, and often the block's insurer for the communal areas, and none of them have any relationship with you or any reason to be reasonable about it.
That is why £2m stops making sense the moment you work above other homes. Pressure testing and physically checking every connection before you leave is the control that prevents almost all of it, and it takes ten minutes at the end of a job.
The Worktop Is Not Third Party Property
While you are handling it, a worktop is arguably in your care, custody or control rather than being somebody else's property, and public liability wordings commonly exclude exactly that. So the pane you crack carrying it in is not a liability claim.
It has to sit under contract works or goods in transit, and a lot of fitters hold neither. Given that a templated stone top is expensive, unique to that kitchen and weeks away from being replaced, this is worth deciding on purpose. Plenty of fitters choose to carry it themselves with a bigger excess, which is fine as a decision and painful as a surprise.
Wet Rooms And The Tickets Behind The Regulated Bits
A wet room stands or falls on the waterproofing under the tiles. If that fails, water goes into the floor structure and the ceiling below, and putting it right means taking the whole room out again. The strip out is yours; the damage to the building is the claim.
On the regulated work, gas needs registration and unvented cylinders need the ticket. Where you sub either out, take a copy of the certificate and check it runs past the end of your job, because if theirs has lapsed the loss lands with you.
Fitted Bedrooms And Fitted Furniture
Most firms fitting kitchens also fit bedrooms, wardrobes and studies, and it is the same joinery skill on a different wall. For insurance it is the easier half of the business, because the thing that makes kitchens and bathrooms expensive to insure is water and fitted bedrooms have none.
What remains is still worth covering properly. You are in an occupied home, so damage to decoration, flooring and the structure you are fixing into is the common claim, and plasterboard with a badly placed fixing is how a wardrobe comes off a wall. Sliding and mirrored doors are the bedroom equivalent of the worktop problem: heavy, brittle, made to measure, and in your care while you carry them upstairs rather than being third party property.
If bedrooms are a real part of your turnover, say so when you quote. A policy rated purely on kitchen and bathroom work is being priced for a water exposure you are not always carrying, and the split is worth having on the schedule.
Kitchen Design Insurance And Showroom Cover
Fitting is one risk. Designing and supplying is another, and a surprising number of firms do all three without the policy reflecting it. What people search for as kitchen design insurance and kitchen showroom insurance are really two extra sections on the same policy.
Where you produce the design, the claim that follows a mistake is financial rather than physical: a layout that does not work, an appliance specified that will not fit the aperture, a run of units ordered to the wrong measurement. Nothing is damaged and the customer is out of pocket, which is professional indemnity territory rather than public liability. Where you only fit to somebody else's plan, you do not need it, and that is worth establishing rather than assuming either way.
A showroom adds a third set of exposures again: the premises, the display kitchens in it, which are expensive and are stock rather than fixtures, customers walking around your site, and business interruption if you cannot trade from it. Customer deposits are the one people forget, because a showroom usually holds money against orders that have not been delivered yet.
Fitters Who Have Had A Water Claim In A Flat
A leak that reaches two flats below produces a claim large enough to reshape a small fitter's premium for years, and often a letter from an insurer you have never heard of.
The way back is showing that the cause has been removed: pressure testing as standard, checking under units before the doors go on, photographing connections at completion. Those are small, specific and exactly what an underwriter wants to hear.
If a claim like that has followed you to renewal, ring 02382 000820 rather than working through comparison sites, because the systems will simply decline you.
How To Choose A Broker As A Kitchen Or Bathroom Fitter
This trade is written by almost every insurer, which makes the quotes look interchangeable and pushes the real differences into the wording. We are an FCA regulated broker and will not tell you we are the best choice. These are the questions that decide it, and they work on any broker including us.
Ask them straight out who pays for a broken worktop.
If the answer is public liability, they have it wrong, and it is the single most revealing question you can ask. A templated stone top is in your care while you are carrying it, which most liability wordings exclude. It needs contract works or goods in transit behind it.
Did they ask whether you work in flats?
It is the question that should change the limit. A leak in a house is a conversation with your customer; a leak in a flat brings the owner below, their insurer and often the block insurer, none of whom have any reason to be reasonable. A broker who quotes £2 million without asking has not read the trade.
Are the goods covered while they sit in the customer's garage?
Units, appliances and worktops routinely wait days on site before they go in. That is neither your premises nor the customer's responsibility, and it is not covered by default. It is an ordinary thing to arrange and an expensive thing to assume.
Have they separated what you fit from what you design?
If you produce the design, a wrong specification is a financial loss with nothing damaged, which public liability does not answer. If you only fit to someone else's plan you do not need professional indemnity. Either answer is fine; not being asked is not.
How do they treat your subcontractors?
Your customer comes to you because you took the job. Cover normally extends to subcontractors working for you, but if their certificate has lapsed or they were not registered for gas or unvented work, the loss stays with you. A broker should tell you what to collect and when.
Does the schedule describe everything you do?
Kitchens, bathrooms, wet rooms, fitted bedrooms and showroom sales are five different exposures that often sit in one business. One trade description standing in for all of them is how a claim gets argued.
Factually, here is what we do against those questions. We raise the worktop and the goods in transit gap before quoting rather than at renewal, we ask whether you work in flats and set the limit from the answer, we ask whether you design as well as fit so professional indemnity is a decision rather than an omission, and we list bedrooms and showroom work separately so you are not rated as though every job carries a water risk. We are a broker, so it goes to several insurers rather than one.
We also insure the plumbers, tilers and electricians who turn up on the same job, so where a claim crosses between trades it is familiar ground. Our own book starts at £86 a year for a sole trader fitter with up to £2 million of public liability, which is a real placed figure rather than an illustration.
What We Need To Quote
- Turnover across kitchens, bathrooms and wet rooms
- Whether you design and supply as well as fit
- Which regulated work you do yourself and which you sub out
- How you check a subcontractor's registration and cover
- Whether you install wet rooms and how you tank them
- Whether you work in flats
- Five years of claims, especially water
Cover that often goes with this
The gaps we most often find sitting next to this policy.
- Plumbers insuranceThe water side of the same job, and where most of these claims originate.
- Flooring and tilingWet room tanking sits across both and carries the biggest rectification cost in either.
- Shopfitters and shop fittingCommercial fit out rather than work in people's homes, and a different risk.
- Tradesman insuranceTools cover, and the conditions on theft from a van overnight.
- Contractors all riskCover for the job itself while it is in progress, before it is handed over.
This policy covers the business. It does not pay you.
Liability, tools and premises cover protects the business against what it owes other people. None of it pays you anything if illness or injury stops you working, and for anybody self-employed that is usually the bigger personal risk of the two. Income protection pays a monthly amount while you cannot work.
Common questions
How much is kitchen fitters insurance?+
Cover starts at £86 a year for a sole trader kitchen or bathroom fitter, for up to £2m of public liability alone. Two things push a real installer above that floor. Working in flats, because a leak reaching the flat below is a third party claim rather than a chat with your customer, and doing the regulated electrical or gas work yourself rather than subbing it out. Call 02382 000820 and we will price it against what you actually take on.
Am I covered if I break a stone worktop?+
Not under public liability, because while you are handling it the worktop is arguably in your care, custody or control rather than somebody else's property, which wordings commonly exclude. It needs contract works or goods in transit behind it, and many fitters have neither. Given a templated top is expensive and weeks from replacement, decide this deliberately rather than discovering it.
What happens if a leak damages the flat below?+
It becomes a third party claim rather than a disagreement with your customer, and it is usually larger than expected. The downstairs owner claims for ceilings, decoration, flooring and possessions, their insurer may come after you directly, and the block insurer can join in for the communal parts. This is why £2m is not enough once you work above other homes.
Who is liable if my subcontractor does the electrics?+
Your customer comes to you, because you took the job and brought them in. Your public liability normally extends to subcontractors working for you, so you are protected against the claim, and insurers would then pursue theirs. The problem is if their cover has lapsed or they were not registered for the work, because then the loss stays with you. Take a copy of the certificate every time.
Does my insurance cover a wet room that leaks?+
It covers the damage, not the wet room. Water into the floor structure and the ceiling below is a public liability claim. Stripping the tiles, tray and fittings out to re-tank the room is your own cost, and it is substantial because everything above the waterproofing has to come out.
What insurance do I need as a kitchen fitter?+
Public liability first, because you are working inside somebody's home and the claim is damage to it. £2 million is the usual starting point and £5 million once you work in flats, where a leak reaching the flat below becomes a third party claim rather than a conversation with your customer. Employers' liability is required as soon as you employ anyone, subject to limited exemptions. Then contract works or goods in transit, which is what actually answers a broken worktop, and tools cover. Add professional indemnity if you design and specify rather than only fitting.
Do I need public liability insurance as a bathroom fitter?+
It is not required by law the way employers' liability is, but in practice you cannot work without it. Housebuilders, letting agents, housing associations and most private customers ask to see it, and bathroom installation carries the highest escape of water frequency of any domestic trade. Bathroom fitter insurance at £1 million is widely available and £2 million is the sensible floor; go to £5 million if you work above other homes. Quotes are sometimes listed as public liability insurance kitchen fitter or as kitchen and bathroom fitter public liability insurance, which is the same thing described back to front.
Is kitchen and bathroom fitter insurance one policy or two?+
One policy, with both trades declared on it. Firms often do kitchens, bathrooms, wet rooms and fitted bedrooms in the same month, and the mistake is letting a single trade description stand in for all of it. Each part carries a different exposure, water being the expensive one, so the schedule should list what you actually take on. A policy rated only for kitchens can be argued over when the claim arrives from a bathroom.
Who insures kitchen and bathroom fitters in the UK?+
It is widely written, which is the opposite problem from a specialist trade: the quotes look interchangeable and the differences are structural. Most trades insurers will cover it, several through brokers rather than direct. What separates placements is whether the worktop and the goods sitting in a customer's garage are actually covered, whether the limit reflects flat work, and whether design is addressed where you do it. Price is rarely what decides whether a claim gets paid here.
Do I need insurance to fit bedrooms and fitted wardrobes?+
Yes, and it is normally the same policy with bedrooms declared alongside the kitchen and bathroom work. The exposure is lower because there is no water, so it is worth having the split on the schedule rather than being rated as though every job is a bathroom. The claims that do happen are damage to the customer's decoration and floors, fixings pulling out of plasterboard, and breaking a made to measure mirrored or sliding door while carrying it in.
Other trades we cover
What our customers say on Google
5.0average from 169 Google reviews
Related reading
Guides from our team on the cover discussed on this page.